FHA 30-Year Fixed: Interest rate offered based on $356,125 loan amount with 7.580% APR and $3,256 monthly payment at 70% loan-to-value (LTV) and 2.153 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
VA 30-Year Fixed: Interest rate offered based on $354,375 loan amount with 7.021% APR and $3,215 monthly payment at 70% loan-to-value (LTV) and 2.074 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
Conventional 15-Year Fixed: Interest rate offered based on $350,000 loan amount with 6.823% APR and $3,971 monthly payment at 70% loan-to-value (LTV) and 2.127 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
Conventional 30-Year Fixed: Interest rate offered based on $350,000 loan amount with 7.285% APR and $3,275 monthly payment at 70% loan-to-value (LTV) and 2.136 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
Jumbo 30-Year Fixed: Interest rate offered based on $950,001 loan amount with 7.347% APR and $8,097 monthly payment at 70% loan-to-value (LTV) and 2.050 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 1, 2026.
Estimated property taxes are based on a 1.05% effective rate for Tulsa County, Oklahoma, applied to the property value for each scenario shown. Rate is median real estate tax paid by households with a mortgage divided by median home value, per the American Community Survey 2020–2024. Taxes shown are an estimate only and vary by property.
Estimated homeowners insurance is based on an average annual premium of $6,111 for Tulsa, OK, divided by twelve. That average covers existing homes of all values in the area, not the property value shown. Insurance shown is an estimate only and varies by property, coverage and carrier.
FHA 30-Year Refinance: Interest rate offered based on $356,125 loan amount with 7.816% APR and $3,316 monthly payment at 70% loan-to-value (LTV) and 2.069 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
VA 30-Year Refinance: Interest rate offered based on $351,750 loan amount with 7.265% APR and $3,287 monthly payment at 70% loan-to-value (LTV) and 2.125 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 1, 2026.
Conventional 15-Year Refinance: Interest rate offered based on $350,000 loan amount with 7.202% APR and $4,043 monthly payment at 70% loan-to-value (LTV) and 2.239 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
Conventional 30-Year Refinance: Interest rate offered based on $350,000 loan amount with 7.548% APR and $3,334 monthly payment at 70% loan-to-value (LTV) and 2.365 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 19, 2026.
Jumbo 30-Year Refinance: Interest rate offered based on $950,001 loan amount with 7.502% APR and $8,177 monthly payment at 70% loan-to-value (LTV) and 2.250 discount points. Payment is Principal, Interest, estimated property taxes and estimated homeowners insurance example only. Rate shown is current as of October 1, 2026.
Estimated property taxes are based on a 1.05% effective rate for Tulsa County, Oklahoma, applied to the property value for each scenario shown. Rate is median real estate tax paid by households with a mortgage divided by median home value, per the American Community Survey 2020–2024. Taxes shown are an estimate only and vary by property.
Estimated homeowners insurance is based on an average annual premium of $6,111 for Tulsa, OK, divided by twelve. That average covers existing homes of all values in the area, not the property value shown. Insurance shown is an estimate only and varies by property, coverage and carrier.
Estimated monthly payment includes principal, interest, estimated Tulsa, OK property taxes, and estimated homeowners insurance.
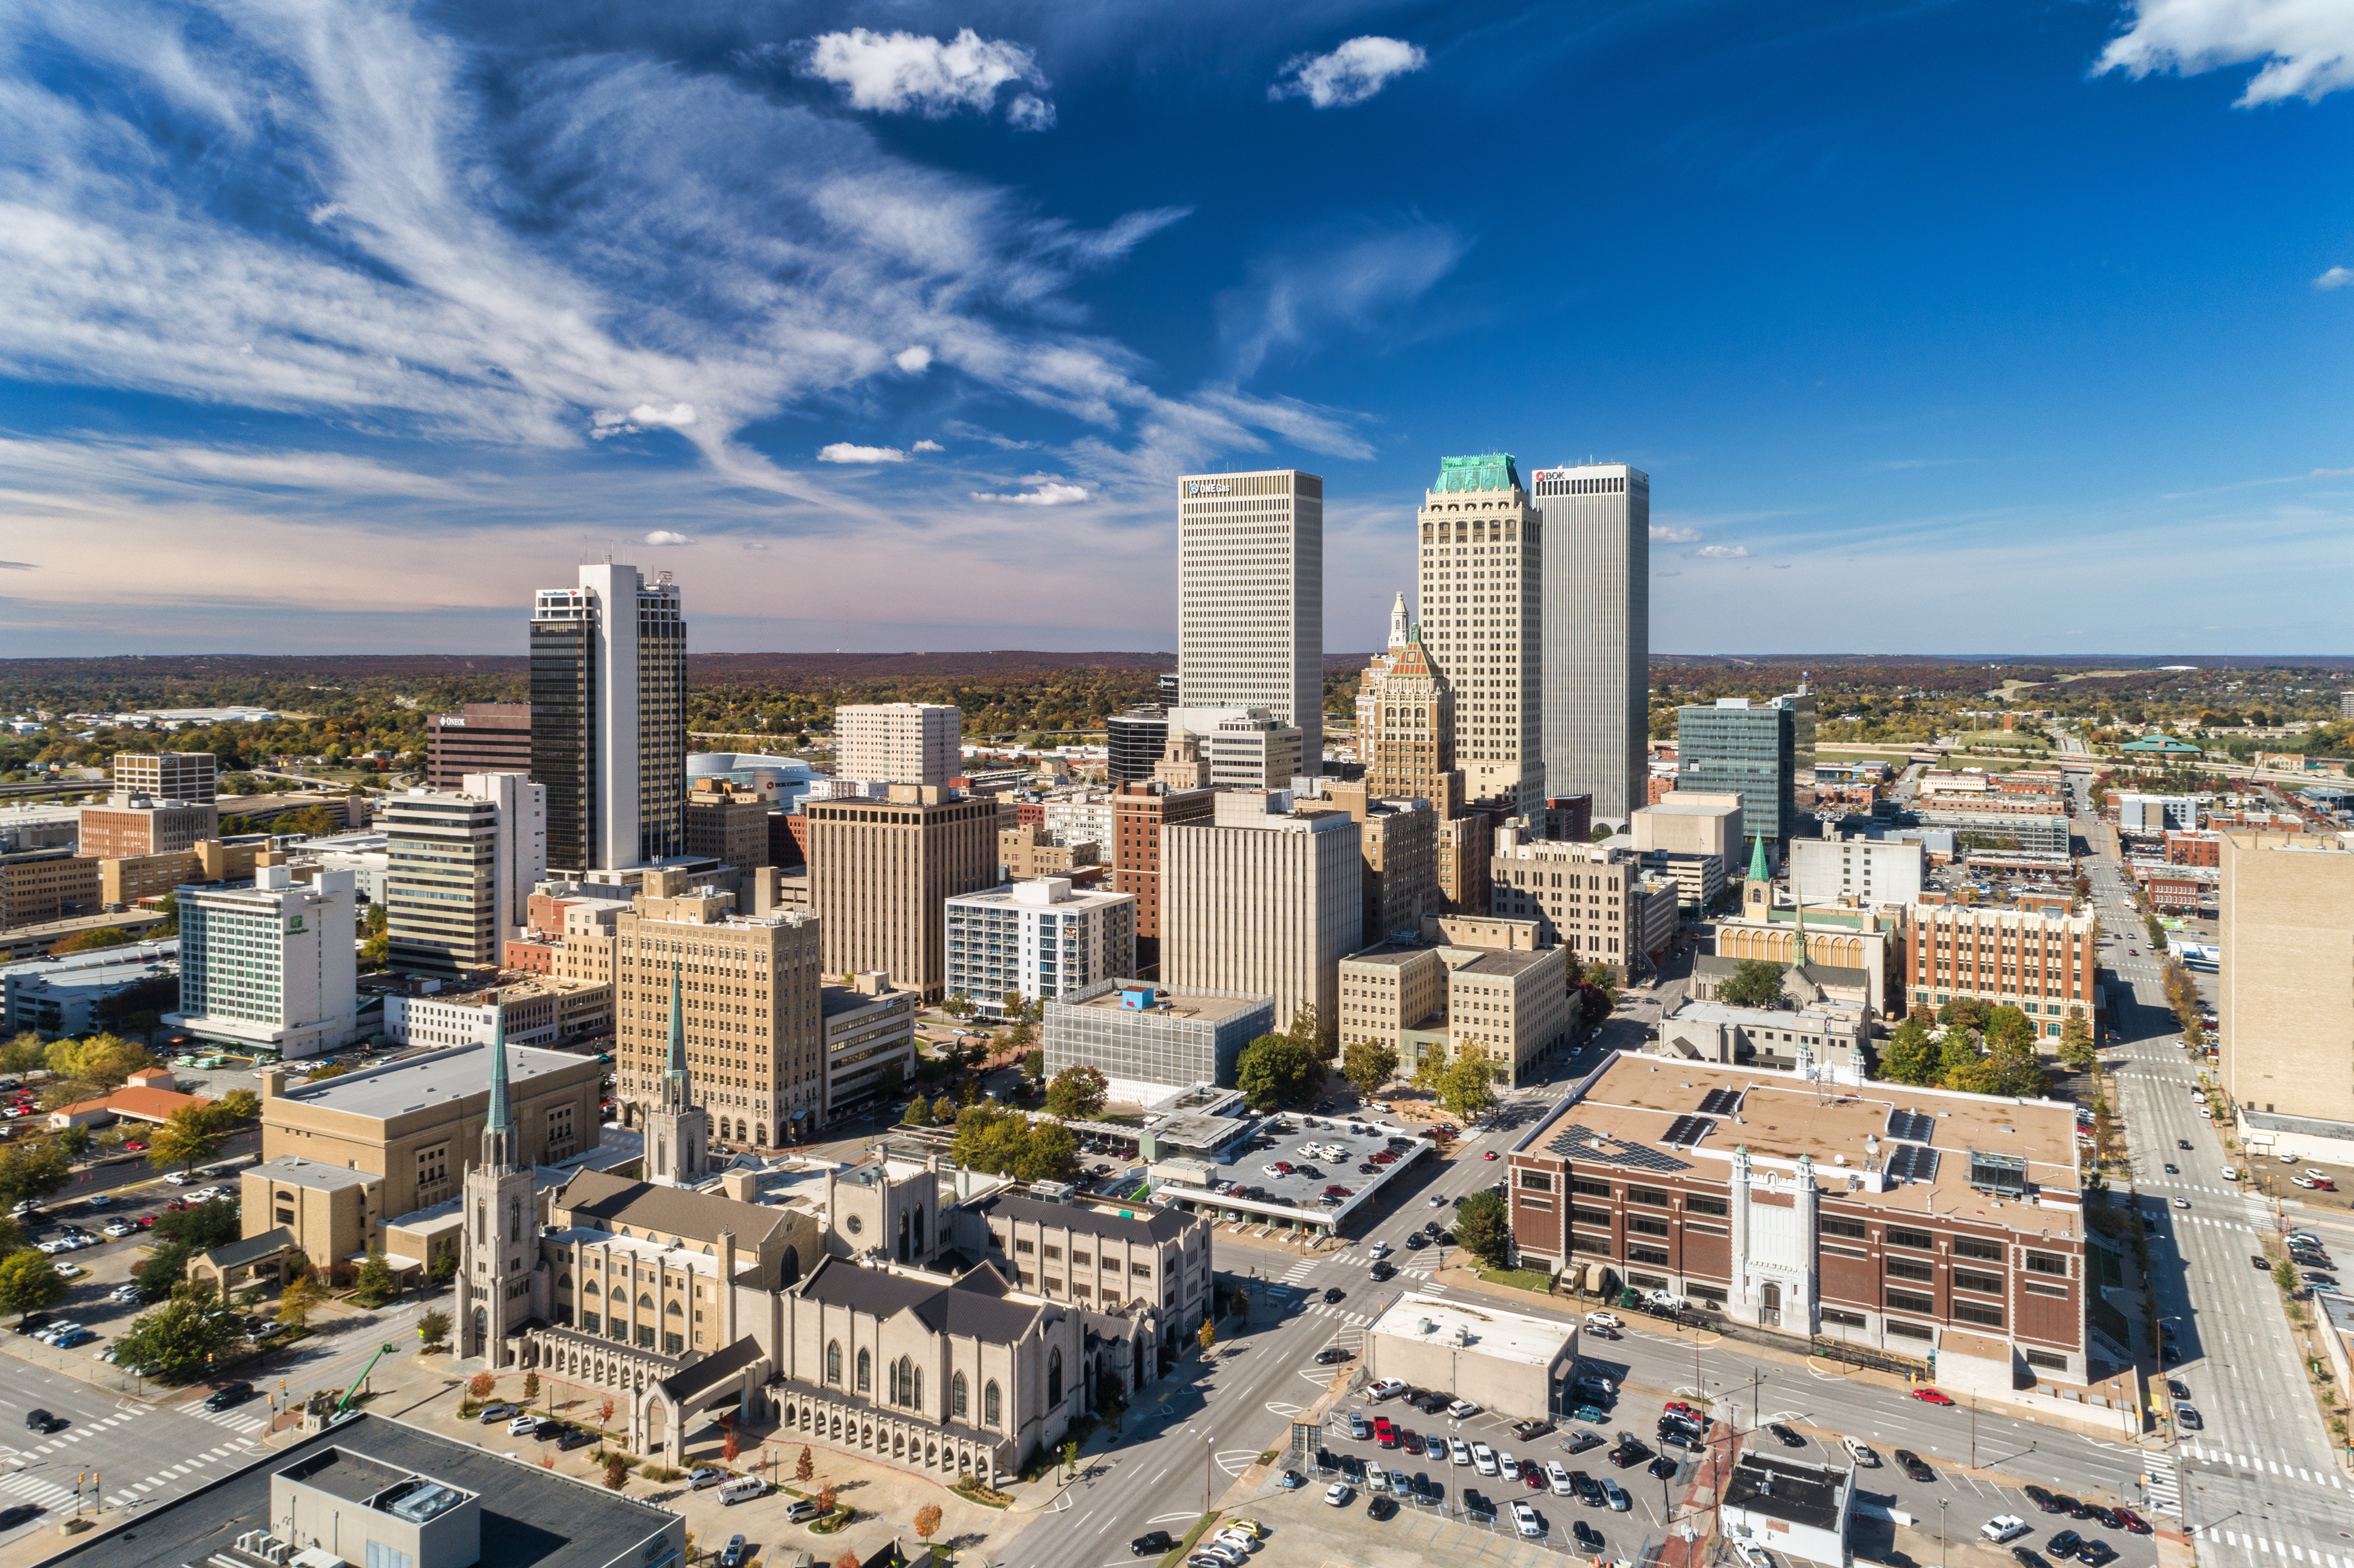
In Tulsa, homes are selling in about 54 days (4 slower than a year ago), sales are up 3.0% from last year, and about 26% of listings have had a price cut.
Monthly payments on Tulsa's median home price of $269,900 (September 2026), at today's rates.
20% down · Conventional
$2,182/mo
Down payment
$53,980
Loan amount
$215,920
Rate
7.000%
Principal & interest
$1,437
Est. property tax
$236
Est. homeowners insurance
$509
5% down · Conventional
$2,451/mo
Down payment
$13,495
Loan amount
$256,405
Rate
7.000%
Principal & interest
$1,706
Est. property tax
$236
Est. homeowners insurance
$509
3.5% down · FHA
$2,464/mo
Down payment
$9,447
Loan amount
$265,011
Rate
6.750%
Principal & interest
$1,719
Est. property tax
$236
Est. homeowners insurance
$509
Payments include principal, interest, estimated Tulsa property taxes, and estimated homeowners insurance. They do not include mortgage insurance (PMI or FHA monthly MIP), which applies with less than 20% down, or HOA dues.
The FHA loan amount includes the 1.75% upfront mortgage insurance premium.
These are examples based on the median price, not the sample loan used in the rate table above.
How much income do you need to buy a home in Tulsa?
A common lender guideline is to keep your total housing payment (principal, interest, estimated Tulsa property taxes, and estimated homeowners insurance) at or below 28% of your gross monthly income. Gross income is what you earn before taxes and other deductions come out of your paycheck. Based on that guideline, here's the yearly household income needed for Tulsa's $269,900 median home:
20% down · Conventional$2,182/mo payment$93,514/yrabout $7,793/mo before taxes
5% down · Conventional$2,451/mo payment$105,058/yrabout $8,755/mo before taxes
3.5% down · FHA$2,464/mo payment$105,614/yrabout $8,801/mo before taxes
Why this matters: Keeping housing costs near 28% of your income leaves room for other bills, savings and the upkeep that comes with owning a home. It's a planning guideline, not a hard limit.
What lenders look at: Lenders also look at your debt-to-income (DTI) ratio, which adds your car, student loan and credit card payments to the new mortgage payment. Depending on the loan program and your credit, many lenders allow total debts of roughly 43% to 50% of gross income, so you may qualify with less income than shown, or need more if you carry other debt.
Household income counts: If you're buying with a partner or co-borrower, lenders can combine your incomes.
How rates change your payment
Principal and interest on a $215,920 loan (the Tulsa median price with 20% down). Every 0.25% is worth about $36/mo.
Rate
6.00%
6.25%
6.50%
6.75%
7.00% today
7.25%
Monthly P&I
$1,295
$1,329
$1,365
$1,400
$1,437
$1,473
Ways to make a Tulsa home more affordable
Negotiate on price. About 26% of Tulsa listings have had a price cut, so many sellers are open to offers.
Ask for seller concessions. Homes take 54 days to sell, 4 more than last year. Sellers may cover closing costs or pay for a rate buydown.
Consider buying down your rate. On this example loan, a rate 0.5% lower saves about $72 a month.
Compare loan types. FHA rates are at 6.750% vs. 7.000% for conventional, with as little as 3.5% down. Compare by APR, including mortgage insurance.
Tulsa mortgage and home buying FAQs
What are mortgage rates in Tulsa today?
As of October 19, 2026, Lower’s 30-year fixed conventional rate in Tulsa is 7.000% (7.285% APR), and the 30-year FHA rate is 6.750% (7.580% APR). Your rate depends on your credit, down payment, loan type and any points you pay. See the rate table above for points and full details.
What is the monthly payment on a median-priced home in Tulsa?
On Tulsa’s $269,900 median home price (September 2026), a 30-year conventional loan with 20% down at 7.000% comes to about $2,182 a month, including principal, interest, estimated Tulsa property taxes, and estimated homeowners insurance. With an FHA loan and 3.5% down, it’s about $2,464 a month before monthly mortgage insurance.
How much income do I need to buy a house in Tulsa?
To keep housing costs at 28% of gross (pre-tax) income, you’d need a household income of about $93,514 a year to buy Tulsa’s $269,900 median home with 20% down, or about $105,614 with an FHA loan and 3.5% down. Lenders also consider your other debts, so the income you need may be higher or lower.
How much do I need for a down payment in Tulsa?
On the $269,900 median home, 20% down is $53,980, 5% down is $13,495, and the FHA minimum of 3.5% is $9,447. Putting less than 20% down usually means paying mortgage insurance. You’ll also need money for closing costs.
Is it a buyer’s or seller’s market in Tulsa right now?
In September 2026, Tulsa homes sold in about 54 days, 4 days slower than a year earlier. 1774 homes sold, up from 1723 the year before, and about 26% of the 1977 homes for sale have had a price cut. Slower sales and frequent price cuts generally give buyers more room to negotiate than a year ago.
How much does a quarter-point rate change affect payments in Tulsa?
On a $215,920 loan (the median Tulsa home with 20% down), each 0.25% change in rate moves the principal and interest payment by about $36 a month, or about $433 a year.
How much are property taxes in Tulsa?
Lower estimates Tulsa property taxes at about 1.05% of a home’s value per year. On the $269,900 median home, that’s roughly $2,834 a year, or $236 a month. Your actual bill depends on your assessed value and any exemptions.
Market data: Movoto, September 2026. Homeowners insurance estimates are based on average annual premiums in Tulsa from The Zebra; your quote will vary. Rates as of October 19, 2026. Examples only; not an offer of credit. Your rate and payment depend on your credit, down payment, loan type and other factors.
Don't take our word for it. We've got 50,000 five-star reviews and counting. Read what real customers have to say. Trustpilot | Google | Zillow | Bankrate
5.0
Mallory always goes the extra mile on every transaction and makes sure everyone is in the loop and educated
Tasha F.
Verified Customer
August 28, 2026
5.0
My Client moved into his new home before school started which was a primary goal for this transaction.
Mark A.
Verified Customer
August 7, 2026
5.0
Mallory worked with an old man who has zero technology skills and somehow got me through all of it. She probably should have lost her cool about 20 times but she remained calm and very professional every time and walked me through every step.
Mark W.
Verified Customer
August 8, 2026
5.0
Mallory was wonderful to work with. She worked hard to provide us with the best option for financing, she was very knowledgeable and answered any questions we had. I know she worked over her normal hours to … make sure we were able to close on time. She explained each step through out the process . We would highly recommend Mallory and will contact her again in the future
Annette W.
Verified Customer
August 31, 2026
5.0
It was very easy to talk to Mallory she made the whole process enjoyable all the way through. I felt I could trust her.
Crystal H.
Verified Customer
June 23, 2026
5.0
Mallory walked us through the whole process with out any hiccups!!!
Thanks
Ben
Benjamin R.
Verified Customer
July 14, 2026
Tasha F. rated Mallory Benne 5.0 stars: Mallory always goes the extra mile on every transaction and makes sure everyone is in the loop and educated
Mark A. rated Mallory Benne 5.0 stars: My Client moved into his new home before school started which was a primary goal for this transaction.
Mark W. rated Mallory Benne 5.0 stars: Mallory worked with an old man who has zero technology skills and somehow got me through all of it. She probably should have lost her cool about 20 times but she remained calm and very professional every time and walked me through every step.
Annette W. rated Mallory Benne 5.0 stars: Mallory was wonderful to work with. She worked hard to provide us with the best option for financing, she was very knowledgeable and answered any questions we had. I know she worked over her normal hours to make sure we were able to close on time. She explained each step through out the process . We would highly recommend Mallory and will contact her again in the future
Crystal H. rated Mallory Benne 5.0 stars: It was very easy to talk to Mallory she made the whole process enjoyable all the way through. I felt I could trust her.
Benjamin R. rated Mallory Benne 5.0 stars: Mallory walked us through the whole process with out any hiccups!!!
Thanks
Ben
Lower Rates. Lower Stress. Free Refi for Life.
We combine a seamless, fully online experience with human expertise to help you get the best possible rate. Applying online comes with no commitment and a no-impact credit check.



 Verified Customer
 50,000+ 5-star reviews