
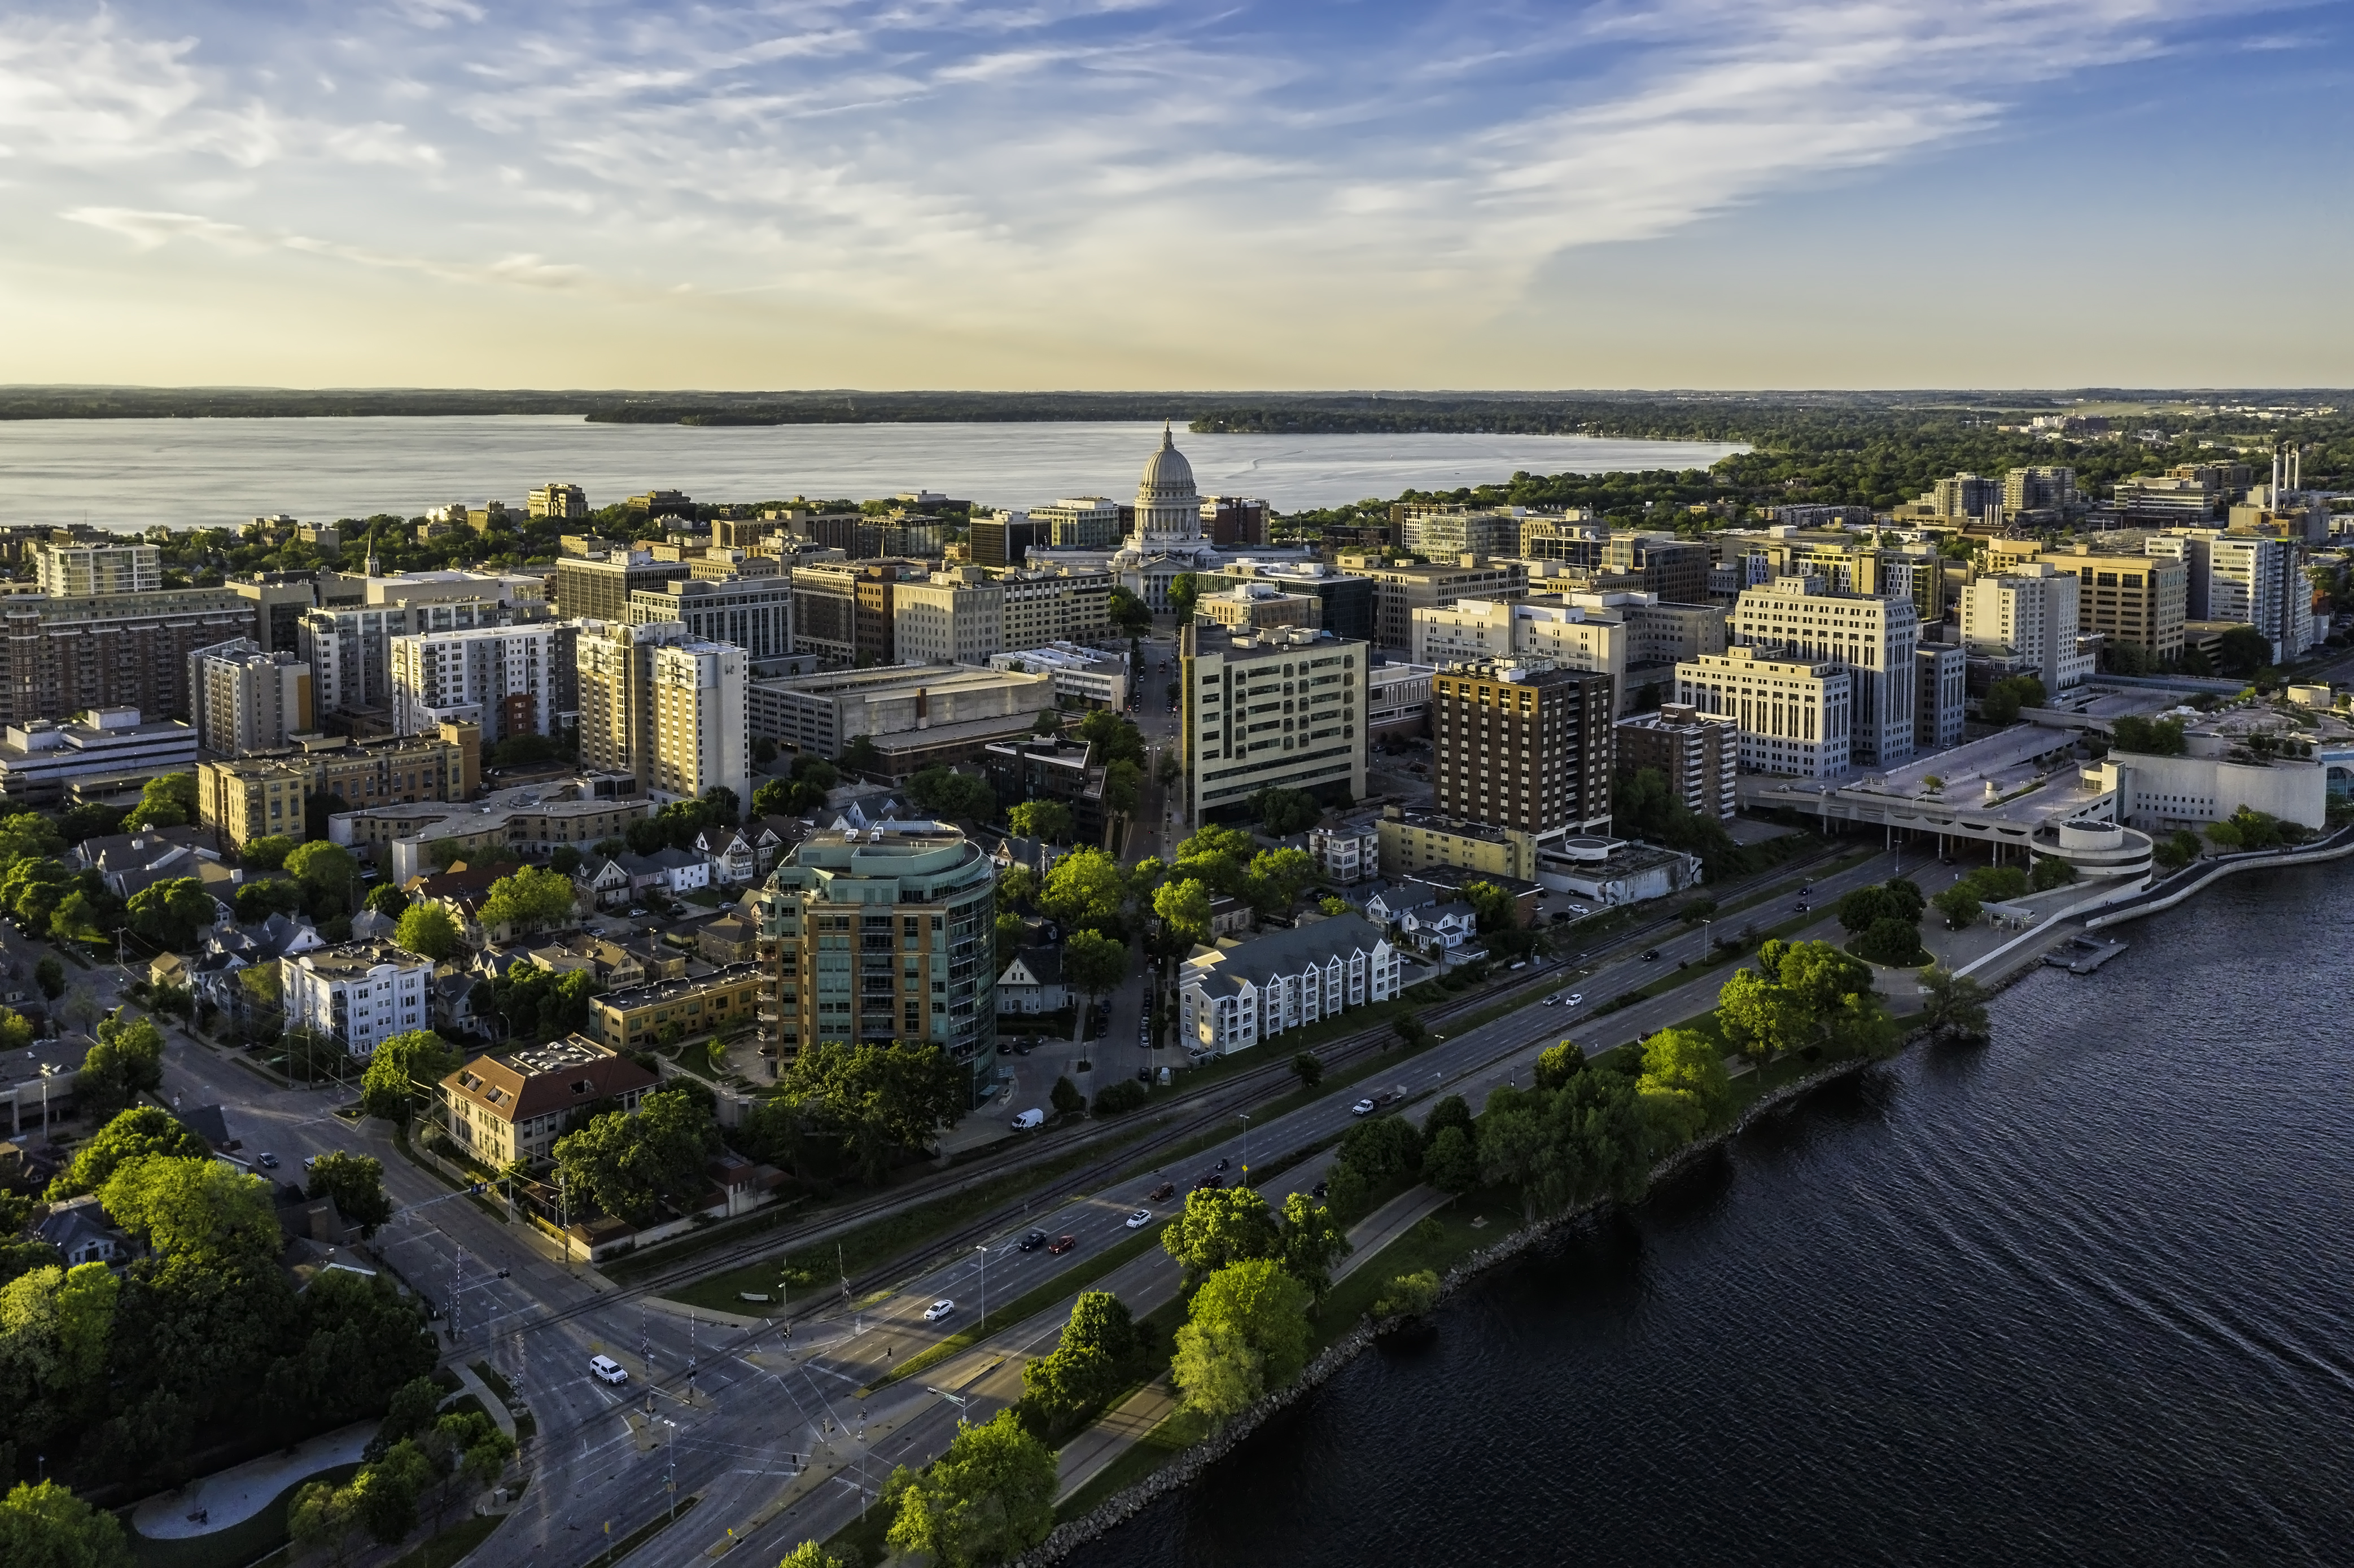
Skip to content

Madison, WI Mortgage Rates Today

Get a Lower rate in Madison, Wisconsin whether you're buying, looking to get cash out of your home or lower your monthly mortgage payment.

No-impact credit check. No commitment.
Madison skyline

Current Mortgage Rates in Madison, WI

Madison housing market at a glance

September 2026 data

In Madison, homes are selling in about 46 days (13 slower than a year ago), sales are up 22.5% from last year, and about 26% of listings have had a price cut.

Median sale price
$450,000
$256 per sq. ft.
Homes sold
767
▲ 22.5% vs. 626 last year
Days on market
46
vs. 33 days last year
Homes for sale
804
48 new listings
Listings with a price cut
26%
209 of 804 listings

Source: Movoto Madison, WI market trends, September 2026. Last updated October 5, 2026.

What it costs to buy a home in Madison

Monthly payments on Madison's median home price of $450,000 (September 2026), at today's rates.

20% down · Conventional
$3,177/mo
Down payment
$90,000
Loan amount
$360,000
Rate
7.125%
Principal & interest
$2,425
Est. property tax
$611
Est. homeowners insurance
$141
5% down · Conventional
$3,632/mo
Down payment
$22,500
Loan amount
$427,500
Rate
7.125%
Principal & interest
$2,880
Est. property tax
$611
Est. homeowners insurance
$141
3.5% down · FHA
$3,655/mo
Down payment
$15,750
Loan amount
$441,849
Rate
6.875%
Principal & interest
$2,903
Est. property tax
$611
Est. homeowners insurance
$141

Payments include principal, interest, estimated Madison property taxes, and estimated homeowners insurance. They do not include mortgage insurance (PMI or FHA monthly MIP), which applies with less than 20% down, or HOA dues. The FHA loan amount includes the 1.75% upfront mortgage insurance premium. These are examples based on the median price, not the sample loan used in the rate table above.

How much income do you need to buy a home in Madison?

A common lender guideline is to keep your total housing payment (principal, interest, estimated Madison property taxes, and estimated homeowners insurance) at or below 28% of your gross monthly income. Gross income is what you earn before taxes and other deductions come out of your paycheck. Based on that guideline, here's the yearly household income needed for Madison's $450,000 median home:

20% down · Conventional$3,177/mo payment $136,170/yrabout $11,347/mo before taxes
5% down · Conventional$3,632/mo payment $155,660/yrabout $12,972/mo before taxes
3.5% down · FHA$3,655/mo payment $156,624/yrabout $13,052/mo before taxes

Why this matters: Keeping housing costs near 28% of your income leaves room for other bills, savings and the upkeep that comes with owning a home. It's a planning guideline, not a hard limit.

What lenders look at: Lenders also look at your debt-to-income (DTI) ratio, which adds your car, student loan and credit card payments to the new mortgage payment. Depending on the loan program and your credit, many lenders allow total debts of roughly 43% to 50% of gross income, so you may qualify with less income than shown, or need more if you carry other debt.

Household income counts: If you're buying with a partner or co-borrower, lenders can combine your incomes.

How rates change your payment

Principal and interest on a $360,000 loan (the Madison median price with 20% down). Every 0.25% is worth about $60/mo.

Rate6.13%6.38%6.63%6.88%7.13%
today
7.38%
Monthly P&I$2,187$2,246$2,305$2,365$2,425$2,486

Ways to make a Madison home more affordable

  • Negotiate on price. About 26% of Madison listings have had a price cut, so many sellers are open to offers.
  • Ask for seller concessions. Homes take 46 days to sell, 13 more than last year. Sellers may cover closing costs or pay for a rate buydown.
  • Consider buying down your rate. On this example loan, a rate 0.5% lower saves about $120 a month.
  • Compare loan types. FHA rates are at 6.875% vs. 7.125% for conventional, with as little as 3.5% down. Compare by APR, including mortgage insurance.

Madison mortgage and home buying FAQs

What are mortgage rates in Madison today?

As of October 9, 2026, Lower’s 30-year fixed conventional rate in Madison is 7.125% (7.418% APR), and the 30-year FHA rate is 6.875% (7.697% APR). Your rate depends on your credit, down payment, loan type and any points you pay. See the rate table above for points and full details.

What is the monthly payment on a median-priced home in Madison?

On Madison’s $450,000 median home price (September 2026), a 30-year conventional loan with 20% down at 7.125% comes to about $3,177 a month, including principal, interest, estimated Madison property taxes, and estimated homeowners insurance. With an FHA loan and 3.5% down, it’s about $3,655 a month before monthly mortgage insurance.

How much income do I need to buy a house in Madison?

To keep housing costs at 28% of gross (pre-tax) income, you’d need a household income of about $136,170 a year to buy Madison’s $450,000 median home with 20% down, or about $156,624 with an FHA loan and 3.5% down. Lenders also consider your other debts, so the income you need may be higher or lower.

How much do I need for a down payment in Madison?

On the $450,000 median home, 20% down is $90,000, 5% down is $22,500, and the FHA minimum of 3.5% is $15,750. Putting less than 20% down usually means paying mortgage insurance. You’ll also need money for closing costs.

Is it a buyer’s or seller’s market in Madison right now?

In September 2026, Madison homes sold in about 46 days, 13 days slower than a year earlier. 767 homes sold, up from 626 the year before, and about 26% of the 804 homes for sale have had a price cut. Slower sales and frequent price cuts generally give buyers more room to negotiate than a year ago.

How much does a quarter-point rate change affect payments in Madison?

On a $360,000 loan (the median Madison home with 20% down), each 0.25% change in rate moves the principal and interest payment by about $60 a month, or about $725 a year.

How much are property taxes in Madison?

Lower estimates Madison property taxes at about 1.63% of a home’s value per year. On the $450,000 median home, that’s roughly $7,335 a year, or $611 a month. Your actual bill depends on your assessed value and any exemptions.

Market data: Movoto, September 2026. Homeowners insurance estimates are based on average annual premiums in Madison from The Zebra; your quote will vary. Rates as of October 9, 2026. Examples only; not an offer of credit. Your rate and payment depend on your credit, down payment, loan type and other factors.

Find Out Why Madison Loves Lower

Don't take our word for it. We've got 50,000 five-star reviews and counting. Read what real customers have to say.
Trustpilot | Google | Zillow | Bankrate
5.0

Ashley's whole team are open to help you, to the best of their capibilities w/ open arms!

Danielle T.
Verified Customer
5.0

The excellent almost 24/7 communication and hard work from Claudia is the only reason we were able to close ! She worked well with my very specific circumstances and was DEDICATED to my case. Extremely happy with resul…ts.

Bryce J.

Verified Customer
5.0

Working with Edgard has been exceptional from the very first transaction. He is the kind of loan officer who looks for solutions, not obstacles, and consistently finds ways to make a deal work. I am genuinely grateful for the dedication he brin…gs to my clients and my transactions. He has made deals happen when other lenders could not, and my buyers have been thrilled with the results. Edgard goes far beyond what is typical in this industry. He is hands‑on with every step of the process—he doesn’t pass tasks off to others, he stays involved and engaged from start to finish. He is honest, patient, and willing to hold a buyer’s hand when needed. Recently, he even took one of my buyers to their own banks to help them gather the required documentation. That level of care is rare. We have closed several transactions together, all successful, and he continues to work diligently all the way through closing. My words may not fully capture how extraordinary he is. He thinks creatively, approaches challenges with an “out‑of‑the‑box” mindset, and is available nights and weekends when the situation calls for it. He truly cares about his clients and the deals he works on, and people feel that immediately. It is not easy in today’s market to find someone like Edgard. I will continue recommending him to my buyers—and to my colleagues’ buyers as well. He is an excellent communicator and even helped keep my nervous sellers calm while representing the buyer. Thank you, Edgard, for your hard‑earned efforts, your care, and your diligence. Respectfully, Laurie Ann von Wald

Laurieann W.

Verified Customer
5.0

Working with Sean was a great experience! He made the home-buying process smooth and easy to understand, was always responsive, and helped us every step of the way. Thank you! :)

Kristina C.

Verified Customer
5.0

Gabriela was always very responsive. She was willing To take time to explain and answer questions. She made the first time home buying experience go as smooth as possible.

Katie S.

Verified Customer
5.0

Sarah was very easy to talk to and answered all of my questions. There was alot i had to do but she made it easy to do

Blake E.

Verified Customer

Lower Rates. Lower Stress. Free Refi for Life.

We combine a seamless, fully online experience with human expertise to help you get the best possible rate. Applying online comes with no commitment and a no-impact credit check.

50,000+ 5-star reviews
Lower rates
Easy online application
Fast closing
Seamless online process

And once you buy a home with Lower, you can refinance for free. For life.

Ready to get your personalized rate?

Clear
Selection