Skip to content

Columbus, OH Mortgage Rates Today

Get a Lower rate in Columbus whether you're buying, looking to get cash out of your home or lower your monthly mortgage payment.

No-impact credit check. No commitment.
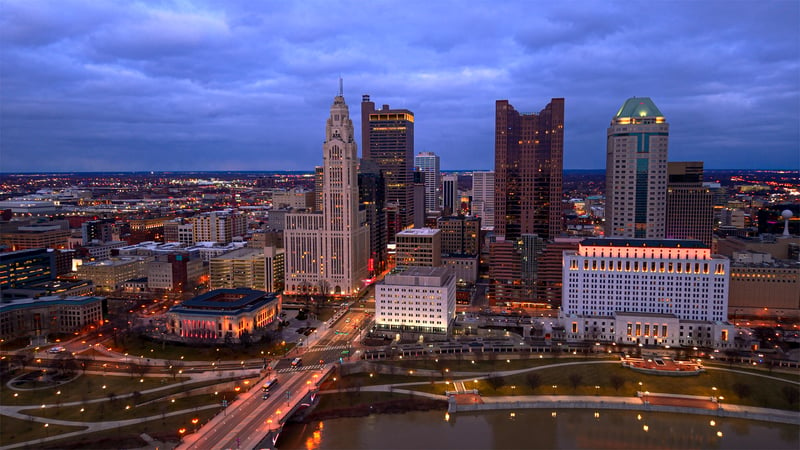
Columbus, Ohio skyline.

Current Mortgage Rates in Columbus

Columbus housing market at a glance

September 2026 data

In Columbus, homes are selling in about 53 days (8 slower than a year ago), sales are up 4.9% from last year, and about 31% of listings have had a price cut.

Median sale price
$270,000
$192 per sq. ft.
Homes sold
2,723
▲ 4.9% vs. 2,597 last year
Days on market
53
vs. 45 days last year
Homes for sale
3,882
325 new listings
Listings with a price cut
31%
1,192 of 3,882 listings

Source: Movoto Columbus, OH market trends, September 2026. Last updated October 5, 2026.

What it costs to buy a home in Columbus

Monthly payments on Columbus's median home price of $270,000 (September 2026), at today's rates.

20% down · Conventional
$1,978/mo
Down payment
$54,000
Loan amount
$216,000
Rate
7.125%
Principal & interest
$1,455
Est. property tax
$335
Est. homeowners insurance
$187
5% down · Conventional
$2,251/mo
Down payment
$13,500
Loan amount
$256,500
Rate
7.125%
Principal & interest
$1,728
Est. property tax
$335
Est. homeowners insurance
$187
3.5% down · FHA
$2,264/mo
Down payment
$9,450
Loan amount
$265,110
Rate
6.875%
Principal & interest
$1,742
Est. property tax
$335
Est. homeowners insurance
$187

Payments include principal, interest, estimated Columbus property taxes, and estimated homeowners insurance. They do not include mortgage insurance (PMI or FHA monthly MIP), which applies with less than 20% down, or HOA dues. The FHA loan amount includes the 1.75% upfront mortgage insurance premium. These are examples based on the median price, not the sample loan used in the rate table above.

How much income do you need to buy a home in Columbus?

A common lender guideline is to keep your total housing payment (principal, interest, estimated Columbus property taxes, and estimated homeowners insurance) at or below 28% of your gross monthly income. Gross income is what you earn before taxes and other deductions come out of your paycheck. Based on that guideline, here's the yearly household income needed for Columbus's $270,000 median home:

20% down · Conventional$1,978/mo payment $84,762/yrabout $7,063/mo before taxes
5% down · Conventional$2,251/mo payment $96,456/yrabout $8,038/mo before taxes
3.5% down · FHA$2,264/mo payment $97,034/yrabout $8,086/mo before taxes

Why this matters: Keeping housing costs near 28% of your income leaves room for other bills, savings and the upkeep that comes with owning a home. It's a planning guideline, not a hard limit.

What lenders look at: Lenders also look at your debt-to-income (DTI) ratio, which adds your car, student loan and credit card payments to the new mortgage payment. Depending on the loan program and your credit, many lenders allow total debts of roughly 43% to 50% of gross income, so you may qualify with less income than shown, or need more if you carry other debt.

Household income counts: If you're buying with a partner or co-borrower, lenders can combine your incomes.

How rates change your payment

Principal and interest on a $216,000 loan (the Columbus median price with 20% down). Every 0.25% is worth about $36/mo.

Rate6.13%6.38%6.63%6.88%7.13%
today
7.38%
Monthly P&I$1,312$1,348$1,383$1,419$1,455$1,492

Ways to make a Columbus home more affordable

  • Negotiate on price. About 31% of Columbus listings have had a price cut, so many sellers are open to offers.
  • Ask for seller concessions. Homes take 53 days to sell, 8 more than last year. Sellers may cover closing costs or pay for a rate buydown.
  • Consider buying down your rate. On this example loan, a rate 0.5% lower saves about $72 a month.
  • Compare loan types. FHA rates are at 6.875% vs. 7.125% for conventional, with as little as 3.5% down. Compare by APR, including mortgage insurance.

Columbus mortgage and home buying FAQs

What are mortgage rates in Columbus today?

As of October 9, 2026, Lower’s 30-year fixed conventional rate in Columbus is 7.125% (7.436% APR), and the 30-year FHA rate is 6.875% (7.697% APR). Your rate depends on your credit, down payment, loan type and any points you pay. See the rate table above for points and full details.

What is the monthly payment on a median-priced home in Columbus?

On Columbus’s $270,000 median home price (September 2026), a 30-year conventional loan with 20% down at 7.125% comes to about $1,978 a month, including principal, interest, estimated Columbus property taxes, and estimated homeowners insurance. With an FHA loan and 3.5% down, it’s about $2,264 a month before monthly mortgage insurance.

How much income do I need to buy a house in Columbus?

To keep housing costs at 28% of gross (pre-tax) income, you’d need a household income of about $84,762 a year to buy Columbus’s $270,000 median home with 20% down, or about $97,034 with an FHA loan and 3.5% down. Lenders also consider your other debts, so the income you need may be higher or lower.

How much do I need for a down payment in Columbus?

On the $270,000 median home, 20% down is $54,000, 5% down is $13,500, and the FHA minimum of 3.5% is $9,450. Putting less than 20% down usually means paying mortgage insurance. You’ll also need money for closing costs.

Is it a buyer’s or seller’s market in Columbus right now?

In September 2026, Columbus homes sold in about 53 days, 8 days slower than a year earlier. 2723 homes sold, up from 2597 the year before, and about 31% of the 3882 homes for sale have had a price cut. Slower sales and frequent price cuts generally give buyers more room to negotiate than a year ago.
How much does a quarter-point rate change affect payments in Columbus?

On a $216,000 loan (the median Columbus home with 20% down), each 0.25% change in rate moves the principal and interest payment by about $36 a month, or about $435 a year.
How much are property taxes in Columbus?

Lower estimates Columbus property taxes at about 1.49% of a home’s value per year. On the $270,000 median home, that’s roughly $4,023 a year, or $335 a month. Your actual bill depends on your assessed value and any exemptions.
Market data: Movoto, September 2026. Homeowners insurance estimates are based on average annual premiums in Columbus from The Zebra; your quote will vary. Rates as of October 9, 2026. Examples only; not an offer of credit. Your rate and payment depend on your credit, down payment, loan type and other factors.

Loan officers in Columbus, OH

Local experts who can walk you through today's Columbus rates, your budget and the loan options that fit.

Brandon Hartley

Senior Loan Officer

NMLS ID# 173898

Leah Severt

Sr. Loan Officer

NMLS ID# 1516506

Reily Kiser

VP of Lending

NMLS ID# 1599098

Nate Ebling

Sr. Loan Officer

NMLS ID# 1377700

Austin Clarkson

Branch Manager, VP

NMLS ID# 1249198

Tyler Marton

Sr. Loan Officer

NMLS ID# 1686334

Sheri Bowman

Sr. Loan Officer

NMLS ID# 72595

Katie Lepley

VP of Sales

NMLS ID# 1618142

Jack Tomlinson

Senior Loan Officer

NMLS ID# 2727244

Todd Ireland

Sr. Loan Officer

NMLS ID# 827776

Trey Bolin

Sr. Loan Officer

NMLS ID# 2796939

Eileen Howard

Branch Manager, VP

NMLS ID# 273082

Mallory Miller

Loan Officer

NMLS ID# 1581071

Connor Kern

Loan Partner

NMLS ID# 2028161

Jose Duarte

Loan Officer

NMLS ID# 2809712

Sam Berman

VP of Lending

NMLS ID# 1964895

Marquise Boykin

Loan Officer

NMLS ID# 2775683

Devin Harris

Loan Officer

NMLS ID# 2848186

Diiamond Lewis

Loan Officer

NMLS ID# 2780085

Owen Dysart

Executive Loan Officer

NMLS ID# 1455697

Heather Bleoo

Loan Officer

NMLS ID# 2800230

Nick Caravana

Senior Executive Loan Officer

NMLS ID# 1416141

Justice Anderson

Loan Officer

NMLS ID# 2416741

Ben Gbur

Senior Loan Officer

NMLS ID# 2755347

Justin Nguyen

Sales Manager

NMLS ID# 2503344

Blake Joe

Senior Loan Officer

NMLS ID# 2755349

Cat Pascual

Senior Executive Loan Officer

NMLS ID# 2503345

Warren Chiapparelli

Executive Loan Officer

NMLS ID# 2003070

Matthew Mikel

Executive Loan Officer

NMLS ID# 1280090

Amber Lee

Loan Officer

NMLS ID# 937408

Tashia Perry

Senior Loan Officer

NMLS ID# 1212600

Dane Shirley

Executive Loan Officer

NMLS ID# 1920925

Shawn Baird

Senior Executive Loan Officer

NMLS ID# 1987654

Sean ONeil

Sr. Loan Officer

NMLS ID# 1287769

Mason Burkhalter

Senior Loan Officer

NMLS ID# 2731699

Amy Cea

Loan Officer

NMLS ID# 2771334

Connor Farley

Sales Manager

NMLS ID# 2516301

Kole Clay

Loan Officer

NMLS ID# 2786965

Cameron Antle

Loan Officer

NMLS ID# 2766639

Miles Juschka

Senior Executive Loan Officer

NMLS ID# 1526616

Joe Bauer

Senior Loan Officer

NMLS ID# 2800233

Griffin Stryker

Senior Loan Officer

NMLS ID# 2047023

Jared Derosa

Senior Executive Loan Officer

NMLS ID# 1692270

Josh Morris

VP of Lending

NMLS ID# 1993042

Brianne Kesner

Executive Loan Officer

NMLS ID# 1373401

Calvin Turner

Loan Officer Assistant

NMLS ID# 2098024

Jake Baynes

Loan Officer

NMLS ID# 2677582

Chris Kirkpatrick

VP of Lending

NMLS ID# 895044

Nico Thomas

Executive Loan Officer

NMLS ID# 2750243

Elijah Chambers

Senior Loan Officer

NMLS ID# 2758009

Andy Payne

Branch Manager, VP

NMLS ID# 2046562

See all Columbus loan officers

Find Out Why Columbus Loves Lower

Don't take our word for it. We've got 50,000 five-star reviews and counting. Read what real customers have to say.
Trustpilot | Google | Zillow | Bankrate
5.0

Jack Tomlinson made the entire mortgage process smooth, efficient, and stress-free. We were working on an expedited timeline, and he delivered every step of the way. His communication was outstanding—he responded quickly, kept us informed throu…ghout the process, and was always available to answer questions, even during some unconventional hours.He consistently looked out for our best interests and made sure we understood every option available.What really set Jack apart was his commitment to customer service. He had no problem going the extra mile to ensure our loan closed on time, and he even attended our closing, which demonstrated his dedication and professionalism.If you’re looking for a lender who is knowledgeable, responsive, and genuinely invested in making the home-buying process as quick and painless as possible, I highly recommend Jack Tomlinson and Lower Mortgage.

Ced N.

Verified Customer
5.0

Graham and his team were wond to work with and quick got my loan done

Cathy S.

Verified Customer
5.0

Every step of the process was clearly explained and quickly handled.

Glenn M.

Verified Customer
5.0

How efficient everything was

Roger B.

Verified Customer
5.0

Josie was honest, communicated frequently and consistiently.

Shannon G.

Verified Customer
5.0

Reily was fantastic to work with! He was very helpful and was always easy to communicate with!

Travis A.

Verified Customer

Lower Rates. Lower Stress. Free Refi for Life.

We combine a seamless, fully online experience with human expertise to help you get the best possible rate. Applying online comes with no commitment and a no-impact credit check.

50,000+ 5-star reviews
Lower rates
Easy online application
Fast closing
Seamless online process

And once you buy a home with Lower, you can refinance for free. For life.

Ready to get your personalized rate?

Clear
Selection